Credit Write-up Agent: AI-generated credit commentary with analyst oversight
From data gathering to decision-making: How AI is transforming credit analysis
A loan application reaching a credit analyst is not the finish line. In many ways, it is where the most demanding work begins.
The analyst must prepare a structured credit write-up, often covering multiple areas. This can include strengths, weaknesses, opportunities, threats, business analysis, security analysis, financial analysis, and a final recommendation. Every section needs evidence, context, and professional judgement.
Why credit analysis needs a new approach
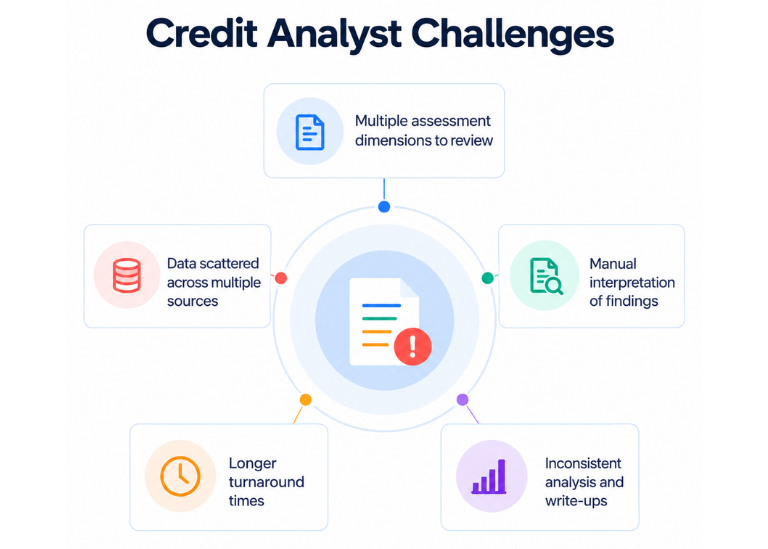
Traditionally, that means opening the company website, reviewing annual reports, checking management structures, finding sector research, reading customer documents, analysing financials, calculating ratios, and comparing year-on-year performance. A single credit write-up can consume most of a working day.
There is another issue: manual drafting is inconsistent. Two analysts reviewing the same borrower can create very different assessments. Some sections may be detailed and well supported, while others may receive limited attention or be overlooked altogether.
The Credit Write-Up Agent changes that starting point. It is an AI agent embedded directly into the loan origination workflow in VeriLoan Loan Origination & Collections Platform. It does not replace the analyst, and it does not make approval decisions. It removes the blank page and much of the repetitive research that comes before expert review.
From blank page to a structured credit assessment
The purpose is straightforward: with one action, the agent researches the borrower across the bank's own data and approved public sources, then creates a fully drafted and sourced credit write-up for the analyst to review.
Instead of moving to a separate portal or tool, the analyst works in the same loan origination and analysis area already used for the credit assessment. The result is a practical starting point, not an automatic lending decision.
The analyst remains responsible for the final assessment. They can review, edit, refine, and sign off on every part of the write-up. The agent is there to reduce research effort and improve consistency across applications.
How the Credit Write-Up Agent works
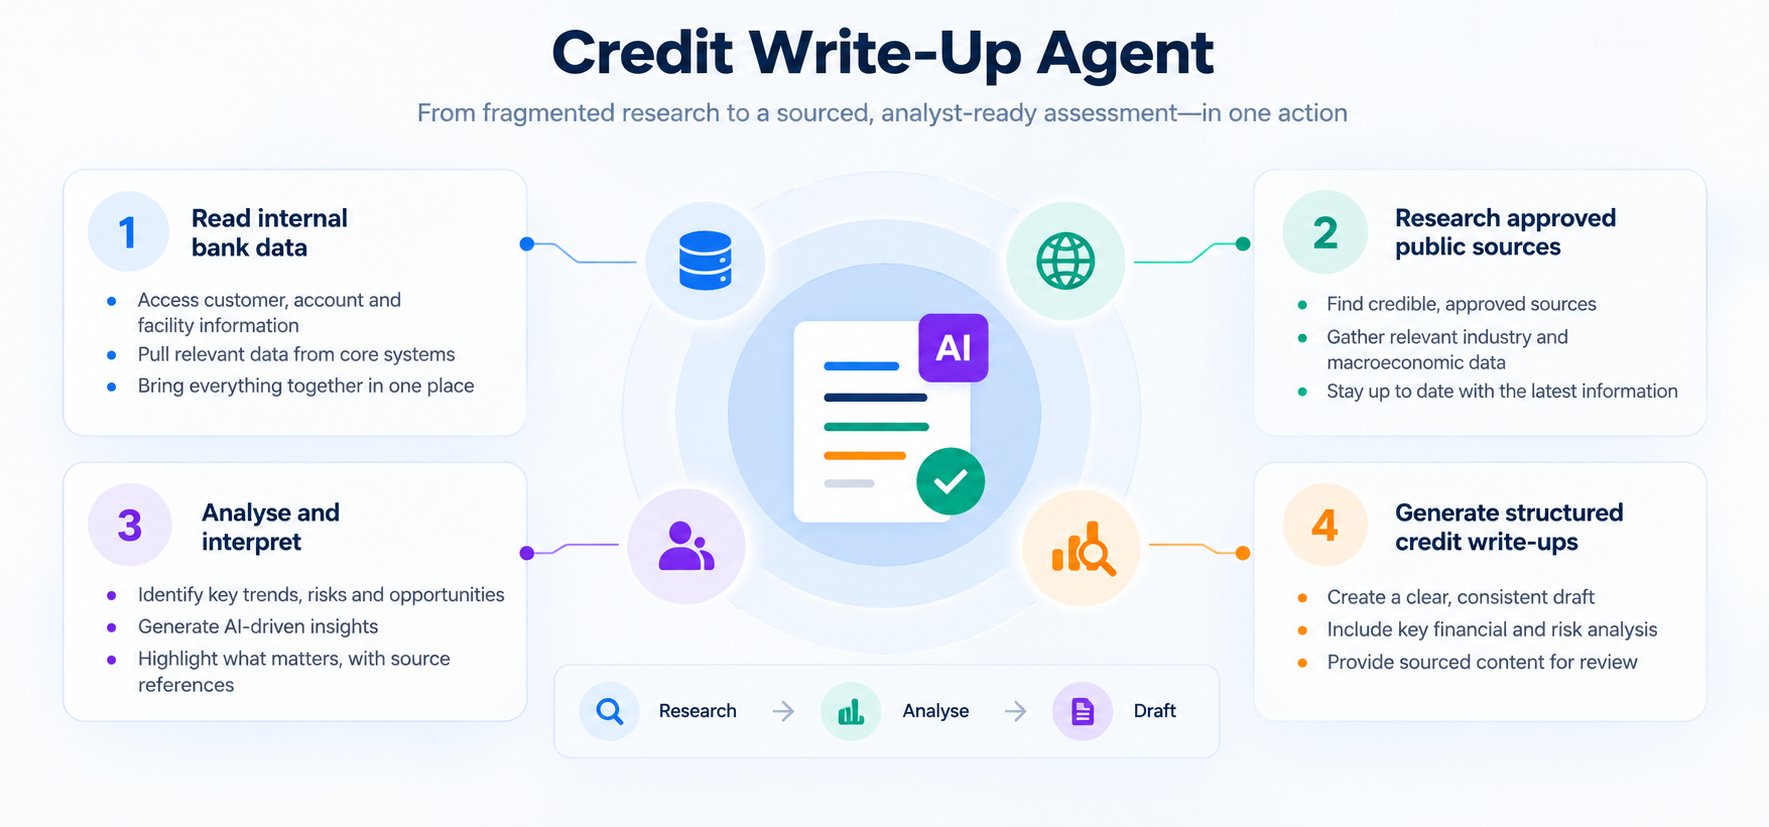
When the analyst selects the option to generate AI insight, the agent follows a four-step sequence.
- Read internal bank data. The agent gathers relevant information from the application, company profile, collaterals, submitted customer documents, and financial data already held in internal systems.
- Research approved public sources. It can use company annual reports, news, market and industry research, and internet search, subject to bank configuration.
- Analyse and interpret. It does not simply repeat information it finds. It compares current financial performance with prior periods, considers sector norms, and forms a structured assessment.
- Map the output into the credit write-up. The analysis is organised into the appropriate sections, with an AI rating and a record of where information came from.
This matters because a good credit write-up is not just a collection of borrower facts. It needs a coherent view of the borrower, the business, the financial trend, and the relevant risk areas. The agent creates that first structured view, allowing analysts to spend their time on interpretation and decision-making.
AI assists, humans make the decisions
Each analysis category can receive an AI rating from a predefined, configurable rating scale. For example, strengths may be assessed as strong while a weakness category may be assessed as moderate.
That rating is useful because it gives the analyst an immediate indication of where the generated assessment sees a positive or negative condition. Information can also be visually highlighted, with positive performance shown in green and weaker performance shown in red, helping important findings stand out.
But the AI rating is not the final rating.
The analyst can provide their own rating for each category. If the AI assesses an area as strong but the analyst determines that moderate is more appropriate, the analyst can make that change. The approval authority considers the analyst rating, not the AI rating.
At the same time, the original AI rating remains recorded for audit purposes. This provides a clear distinction between the machine-generated starting point and the analyst’s final assessment, supporting transparency and accountability while ensuring that credit decisions remain under human control.
Control over data and sources
Risk and compliance teams naturally need to ask an important question: what exactly can the agent read?
The Credit Write-Up Agent is designed so that the bank controls its permitted sources. Internal data ingestion and public-source ingestion can be enabled or disabled. Public domains can be whitelisted, and untrusted domains can be blacklisted.
In other words, the bank decides which information the agent is allowed to use. An administrator can update the configuration according to the bank's policies and operational requirements.
The same principle applies to financial data. The agent does not invent numbers. It uses financial information from the company profile and the application financials, including newly submitted figures where applicable. That gives the credit write-up a documented basis in the data available to the bank.
A first draft is still a draft. Sometimes it is sufficient, but sometimes the analyst needs a more specific angle or an additional data point. This is where the Credit Write-Up Chat Agent comes in.
Refining each section with the Credit Write-Up Chat Agent
The analyst can select one analysis category, such as financial analysis, and ask for a targeted enhancement. The system presents the current generated insight and asks for the additional requirement. Rather than regenerating the entire credit write-up, the chat agent updates only the selected category.
Consider liquidity analysis. The financials may already be available in the application and the underlying system may already have calculated the relevant ratios. But the original draft may not have specifically discussed the current ratio, quick ratio, or cash ratio.
The analyst can request that liquidity ratios be included in the financial analysis. The chat agent retrieves the relevant financial information and ratios, reanalyses the selected section, and presents an enhanced version for review.
The analyst then decides whether to accept the proposed update. If approved, the enhanced analysis is inserted into the relevant application section. It is still not finalised automatically. The analyst can edit the text manually, refine the conclusion, and set the final rating.
What this changes for lending teams
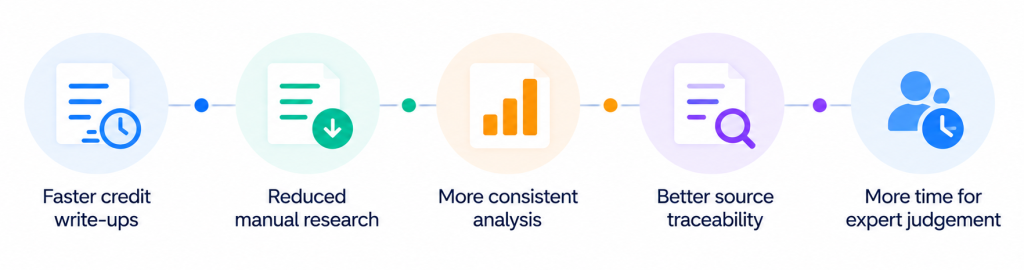
The real benefit is not simply that AI can produce text. It is that the credit write-up process becomes more structured, consistent, and efficient while preserving human accountability.
- Analysts spend less time gathering scattered information from internal and public sources.
- Credit write-ups begin from a complete, structured draft instead of a blank page.
- Financial comparisons, sector context, and risk observations can be included more consistently.
- Bank-controlled sources, rating scales, and audit records support governance requirements.
- Analysts retain authority to edit findings, set ratings, and make the final credit assessment.
The feature consists of two connected capabilities: the Credit Write-Up Agent, which generates the initial populated write-up, and the Credit Write-Up Chat Agent, which refines a specific category through direct interaction.